
Liquidity
Putting more money down may reduce the payment, but preserving capital can sometimes matter more.
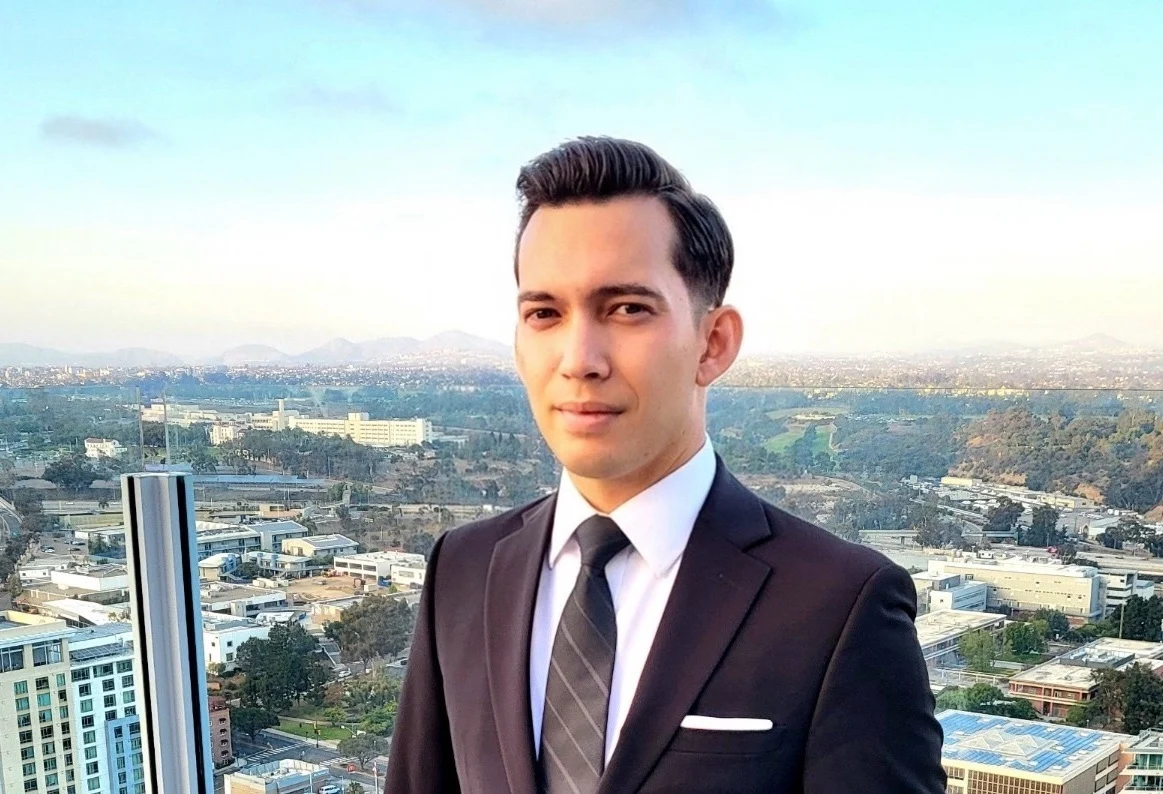
Mortgage Broker • Real Estate Professional • U.S. Army Veteran
Mortgage strategy built on experience behind the file.
Jonathan's background spans mortgage operations, high-volume loan processing, Non-QM lending, real estate, and borrower advisory — giving him a perspective that starts well before a rate is quoted and continues through underwriting and closing.
Jonathan Toth — NMLS #2401903 | CA DRE #02179024
How I got here
Jonathan’s introduction to mortgage lending started on the operational side of the business. His mother worked in mortgage and taught him how loans actually move from application through underwriting, conditions, closing, and funding. That foundation led Jonathan into mortgage processing and high-volume mortgage operations, where he learned that behind every approval is a file that has to make sense. Income has to be documented correctly. Assets have to be sourced. Conditions have to be anticipated and cleared. The property, appraisal, title, insurance, and timing all have to come together before anyone gets keys.
That experience became especially valuable in Non-QM lending, where strong borrowers do not always fit neatly into traditional underwriting. A business owner’s tax returns may not tell the complete story of the business’s cash flow. Investors may care more about property cash flow than personal income. A borrower may have substantial assets but unconventional earnings. A perfectly financeable scenario can look difficult when evaluated through the wrong lens.
Working behind the file taught Jonathan to look beyond whether a loan works on paper and think several steps ahead about how it will actually get to the closing table. Today, the conversation begins with: “What are you trying to accomplish — and what is the strongest way to structure it?”
The HomeFlow approach
A mortgage is one piece of a larger financial decision. Rate matters. But so do cash to close, monthly payment, liquidity, leverage, opportunity cost, taxes, the property itself, how long you expect to keep the loan, and what you plan to do next.
"The question isn't simply, 'What's the lowest rate?' It's, 'What does this mortgage need to accomplish?'"
Putting more money down may reduce the payment, but preserving capital can sometimes matter more.
Points, refinancing costs, and rate decisions should be evaluated against how long you realistically expect to keep the loan.
For investors and sophisticated borrowers, the cheapest debt is not automatically the most productive use of capital.
Income, assets, property type, occupancy, and long-term objectives can completely change which financing strategy makes sense.
Traditional financing is often the right answer when a borrower's finances fit traditional documentation. But business owners, investors, entrepreneurs, borrowers with substantial assets, and people with multiple or unconventional income streams often require a different analysis.
Tax returns don't always tell the complete story. Bank statements, P&Ls, assets, and other documentation may create additional ways to evaluate income.
DSCR, leverage, liquidity, cash flow, property strategy, and exit plans can matter as much as the rate itself.
VA financing is a powerful benefit with its own rules, opportunities, and strategic considerations. It deserves to be understood rather than treated as simply another loan product.
Significant liquidity and investment assets may create qualification strategies that traditional income analysis overlooks.
Complex financing is a specialty — not a requirement. Conventional, FHA, VA, jumbo, and straightforward financing still deserve the same level of analysis.
Beyond the loan
Jonathan is also a California real estate professional and closely follows real estate and investment markets. That perspective matters because a mortgage does not exist in isolation from the property being financed.
For a homebuyer, financing affects affordability, liquidity, and flexibility. For an investor, it can affect leverage, cash flow, return on capital, and the ability to pursue the next opportunity. Understanding both sides of the transaction helps Jonathan discuss financing in the context of the property and the borrower’s broader objective.
Outside the office
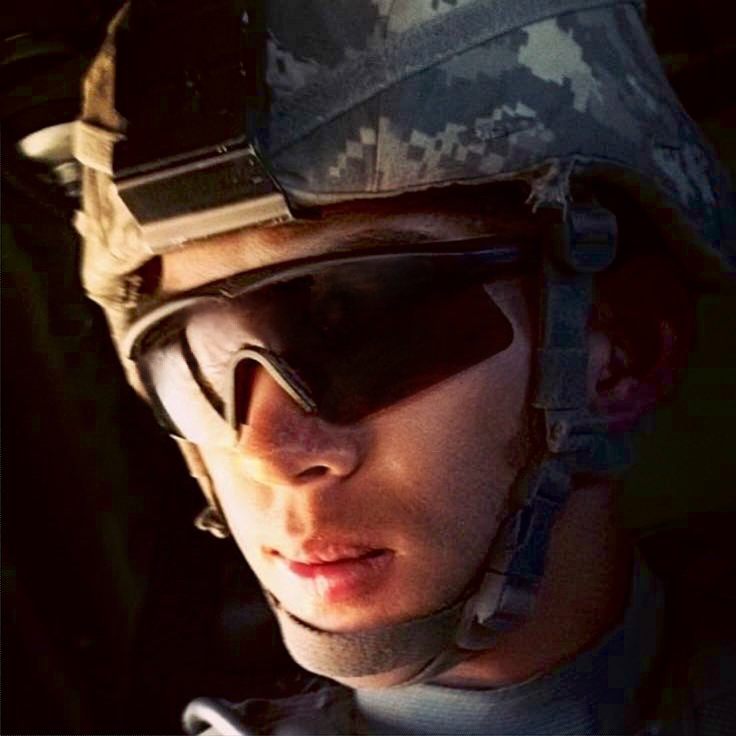
Before mortgage and real estate, Jonathan served in the U.S. Army from 2011 to 2017. The interests that followed look different, but the mindset is remarkably similar.
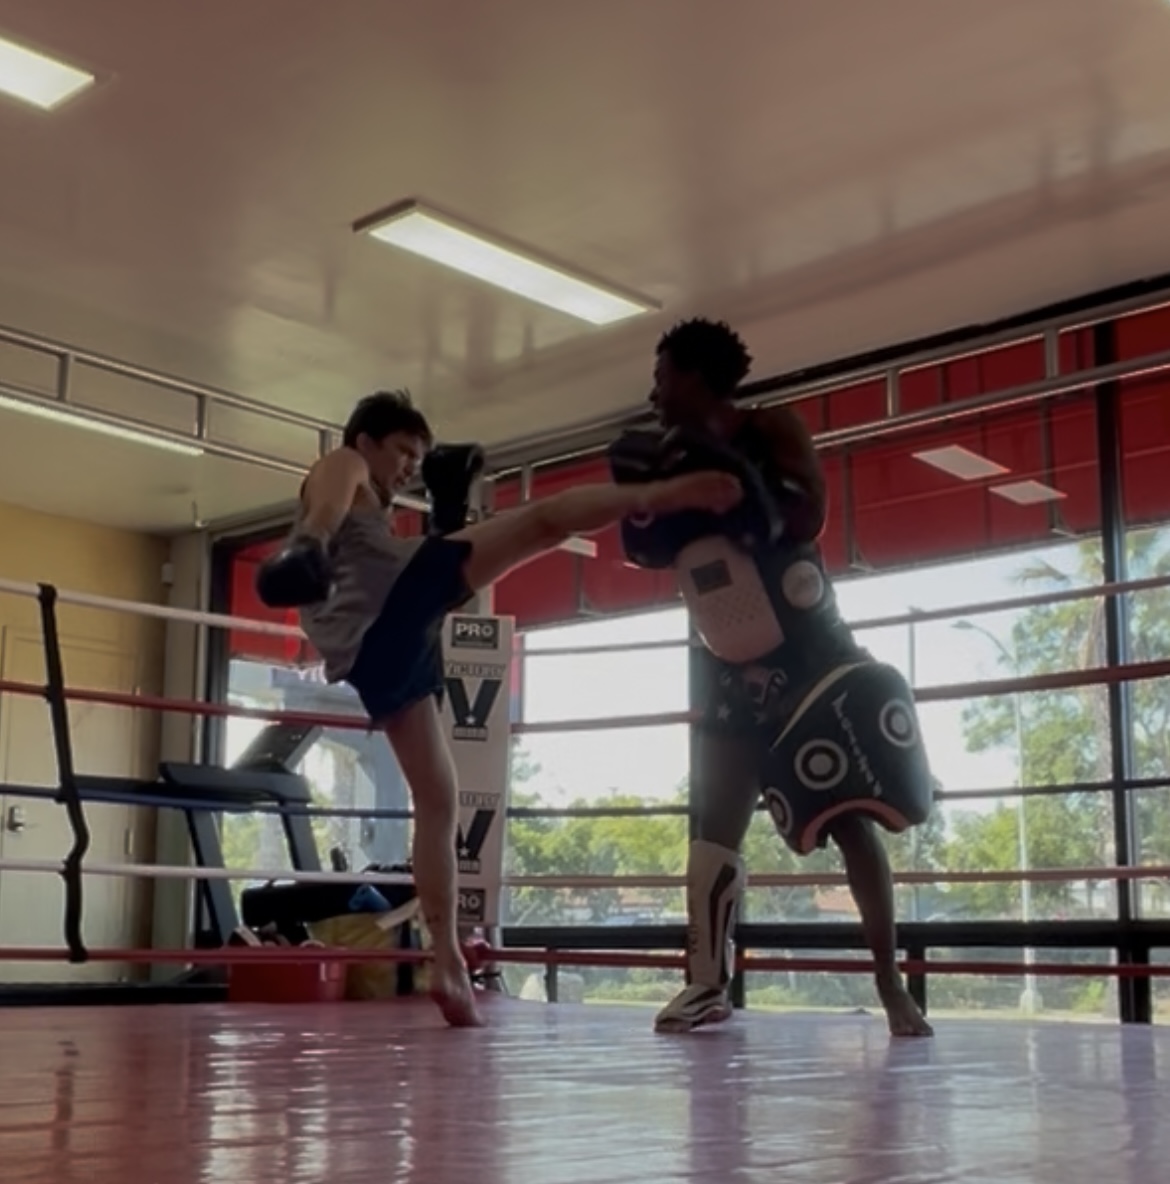
He trains Muay Thai, follows financial and investment markets, studies business and real estate, and has a habit of going deep on whatever he decides is worth learning. That curiosity is part of what ultimately shaped HomeFlow: understand the details, challenge the obvious answer, and keep improving the strategy.
Experience at a glance
NMLS #2401903
CA DRE #02179024
2011–2017
Brokerage
Cascada Mortgage Advisors, Inc. DBA HomeFlow — NMLS #2470941, CA DRE #02206556
Responsible Broker of Record: Omar Michel, CA DRE #02131389
Company licenses are held by Cascada Mortgage Advisors, Inc. DBA HomeFlow. Jonathan Toth is individually licensed under NMLS #2401903 and CA DRE #02179024.
Start with what you're trying to accomplish. We'll work backward from there.